Cato Research Fellow Warns Crypto Bill Progress Could Unravel in New Congress
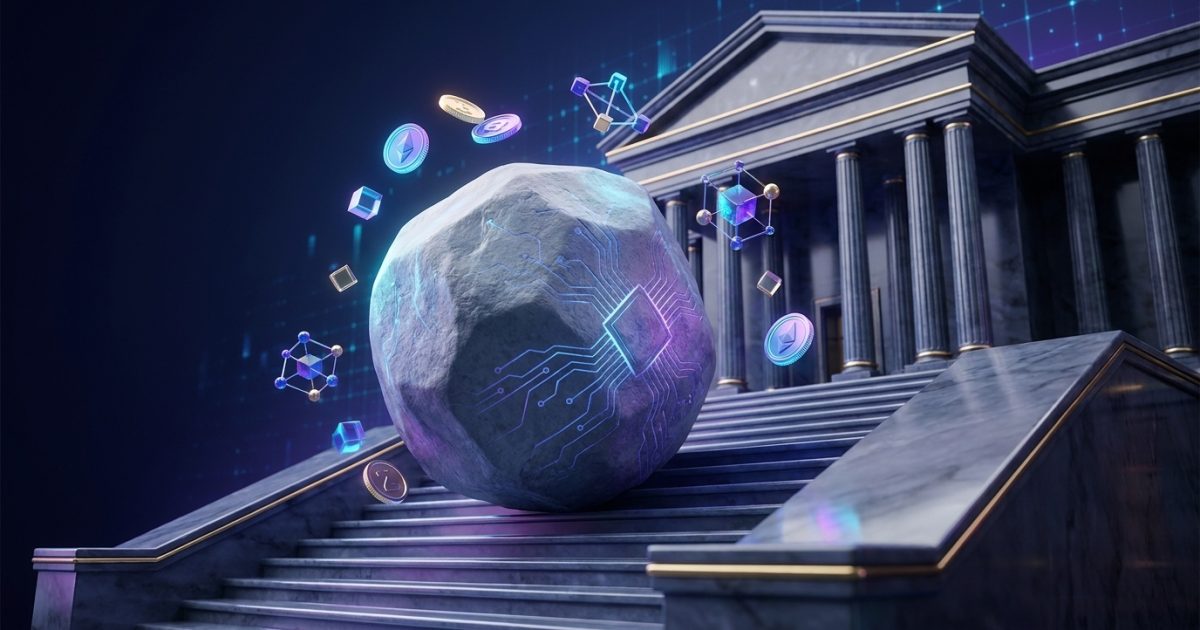
A prominent libertarian think tank scholar has issued a stark warning about the prospects for crypto legislation in Washington, arguing that the industry’s legislative push resembles a Sisyphean struggle in which hard-won progress risks being undone each time the political cycle turns over.
Ryan Chan-Wei, a research fellow at the Center for Monetary and Financial Alternatives at the Cato Institute, wrote in a CoinDesk opinion piece published this week that legislative progress on crypto will “effectively reset” when the new Congress is sworn in. His reasoning is procedural rather than partisan: the key senators who quarterbacked the bill through the upper chamber will not be on the ballot again, removing the institutional knowledge, negotiating relationships and personal investment that drove the effort forward.
The piece, titled “Crypto’s Sisyphean struggle,” arrives at a moment when the digital asset industry has devoted enormous resources to securing federal legislation, only to confront the reality that congressional arithmetic can change faster than bills can cross the finish line.
The metaphor is pointed. In Greek myth, Sisyphus is condemned to roll a boulder up a hill, only for it to roll back down each time he nears the summit. Chan-Wei’s argument is that crypto legislation in the United States faces a structurally similar dynamic: momentum builds across a congressional session, committee chairs and rank-and-file champions invest political capital, drafts are negotiated and amended, and then the two-year cycle expires. A new Congress arrives with new personnel, new priorities and, in some cases, the departure of the very lawmakers who understood the subject matter best.
Who Is Ryan Chan-Wei?
The author’s background lends the argument particular weight. Chan-Wei is not a typical outside commentator. Before joining Cato, he worked as a central banker and financial regulator, with hands-on experience spanning payments and digital assets policy, banking supervision and resolution, and capital markets enforcement. That resume means he has sat on the other side of the table from the industry he now studies, and he understands how regulatory machinery actually operates rather than how it is caricatured.
He has also served as a member of the Future of Payments Working Group convened under the auspices of the Bank for International Settlements’ Committee on Payments and Market Infrastructures, the global standard-setting body that shapes how central banks and supervisors think about payment systems. He is a graduate of Harvard Law School and the University of Oxford.
At Cato’s Center for Monetary and Financial Alternatives, his research focuses primarily on issues relating to financial innovation, placing him in a policy tradition that is sceptical of heavy-handed regulation but also fluent in the technical realities of supervision. That combination makes his pessimism about the legislative timeline notable. When a scholar with regulator credentials and a free-market institutional home says the crypto bill is stuck in a repeating cycle, market participants tend to listen.
The warning is especially relevant for readers following regulation coverage, where the question of whether Congress can actually pass durable crypto statutes has become the defining issue of the current cycle.
Why Congressional Turnover Matters More Than Partisan Control
The core of Chan-Wei’s argument is that legislative progress on complex financial legislation is unusually dependent on individual lawmakers. Bills of this kind, which touch jurisdictional boundaries between banking and securities regulators, require champions who have spent months or years mastering the details. Those champions negotiate with counterparts, build trust with stakeholders on both sides of the aisle, and develop a feel for where compromise is possible.
When those senators depart, whether through retirement, electoral defeat or a decision not to seek re-election, that accumulated capital leaves with them. The new Congress inherits the text of a bill, perhaps, but not the relationships or the tacit understanding of what each provision was designed to achieve. Staff turnover compounds the problem. Committee staff who lived through the drafting process disperse, and their replacements must reconstruct the rationale behind every clause.
This is not a phenomenon unique to crypto. Financial services legislation has historically taken multiple Congresses to enact, with major structural reforms often requiring years of iteration before the political stars align. But the crypto industry’s situation is arguably more acute, because the underlying technology and market structure continue to evolve while the legislative process grinds slowly forward. A bill drafted for the market of two years ago may address a landscape that has already shifted by the time it reaches the floor.
The Sisyphean framing also captures a subtler dynamic: each reset is not merely a delay but an opportunity for opponents to regroup. Interest groups that lost ground in one Congress can reopen fights in the next. Provisions that were settled can be unsettled. The industry, in other words, does not get to resume from its previous position; it must re-litigate terrain it thought it had already won.
For a sector that has invested heavily in lobbying and campaign contributions, this is an uncomfortable conclusion. Money can buy access and attention, but it cannot buy continuity of personnel. If the quarterbacking senators are gone, the playbook goes with them.
Market and Regulatory Implications
The immediate market implication is a repricing of expectations. Traders and executives who had assumed that a legislative breakthrough was a matter of when, not if, must now weigh the possibility that the when keeps receding. Legislative uncertainty tends to suppress institutional participation, because compliance officers and general counsels at banks, asset managers and payment firms struggle to underwrite business lines when the governing framework may change with each election cycle.
There is also a regulatory implication. If Congress cannot legislate, the default regulator remains the agency or agencies that already claim jurisdiction, operating through enforcement actions, guidance documents and rulemaking rather than statute. Chan-Wei’s background as a former regulator is instructive here: policymakers who have worked inside supervisory agencies generally understand that regulation by enforcement is a poor substitute for clear statutory mandates, both for the regulator and for the regulated. Yet a stalled Congress leaves little alternative.
The global dimension deserves attention too. Chan-Wei’s service on a BIS-convened working group on the future of payments reflects the fact that other jurisdictions are not standing still. Central banks and standard-setters abroad are actively developing frameworks for digital assets and payment innovation. If the United States remains locked in a cycle of legislative resets, the risk is not only domestic uncertainty but a gradual migration of standards-setting influence to jurisdictions that can move faster. Global firms build to the strictest coherent regime they can find, and incoherence in Washington pushes them to look elsewhere.
For the industry itself, the argument suggests a strategic question. If legislative progress is hostage to the careers of a handful of senators, then the industry’s task is not merely to win the current Congress but to build a bench of champions across both parties and both chambers, so that no single departure can trigger a reset. That is slower, less glamorous work than a headline legislative push, but it may be the only way to break the cycle.
Closing Analysis
Chan-Wei’s warning is best read not as a prediction of failure but as a description of structural risk. The Sisyphean metaphor implies futility, but the myth’s lesson cuts both ways: the boulder only stays at the bottom if the pusher stops. The crypto industry has shown, through repeated cycles of boom, bust and regulatory confrontation, a persistent willingness to keep pushing.
The realistic assessment is that federal crypto legislation in the United States remains a multi-Congress project. Each session produces drafts, hearings and incremental convergence, and each turnover of personnel erodes some of that progress. Whether the next Congress can convert inherited momentum into statute depends on factors the industry cannot control: committee assignments, electoral outcomes and the willingness of new lawmakers to invest in a technically demanding subject.
What the industry can control is durability of advocacy. The lesson of the Sisyphean struggle, as Chan-Wei frames it, is that progress measured in individual careers is fragile, while progress embedded in institutional knowledge and bipartisan consensus is resilient. For now, the sober conclusion for market participants is to plan for continued regulatory ambiguity, to treat any single Congress’s legislative momentum as provisional, and to watch personnel changes on the relevant committees as closely as the bills themselves. In Washington, the boulder rolls back more often than it reaches the summit, and the smart money prices that in.